Settlement and destination continuity
Settlement is proof-native value, with its authority grounded in verified sources and ownership history. Value sets the standard: a receiving institution must demonstrate that it can verify the source, preserve ownership and history, and maintain proof continuity. Conformance qualifies the receiving destination for this protocol. Each transfer follows your authorization and verification of its current proof and ownership.
Reserve
Reserve is proof-backed funds designated for funded settlement and compatible external payment rails. A deposit becomes available when its funding proof verifies, including the credited amount and receiving account.
How notes work
A funded Reserve Note keeps value with its proof in an original image. Save it on your device, transfer its ownership to a recipient, or deposit it back into Reserve. The two note designs identify their value clearly: proof-backed Reserve and proof-native Settlement. Keep the original PNG: a screenshot or converted photo can lose the proof inside it. A picture alone never establishes ownership or credits a balance.
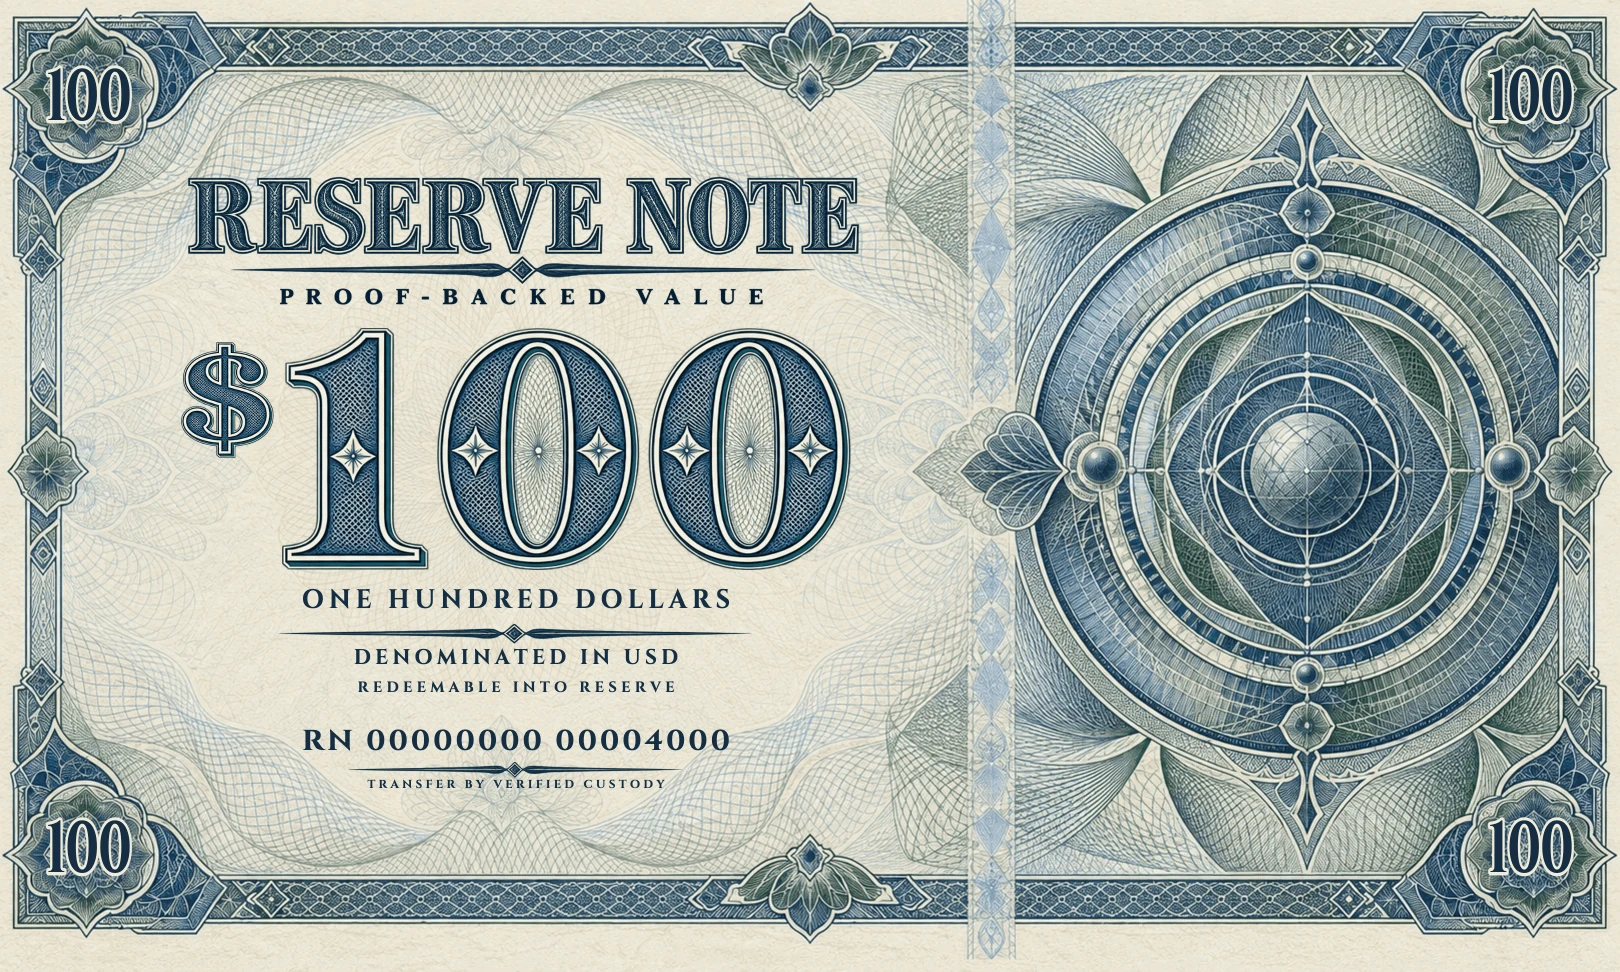
Reserve Note
Proof-backed value.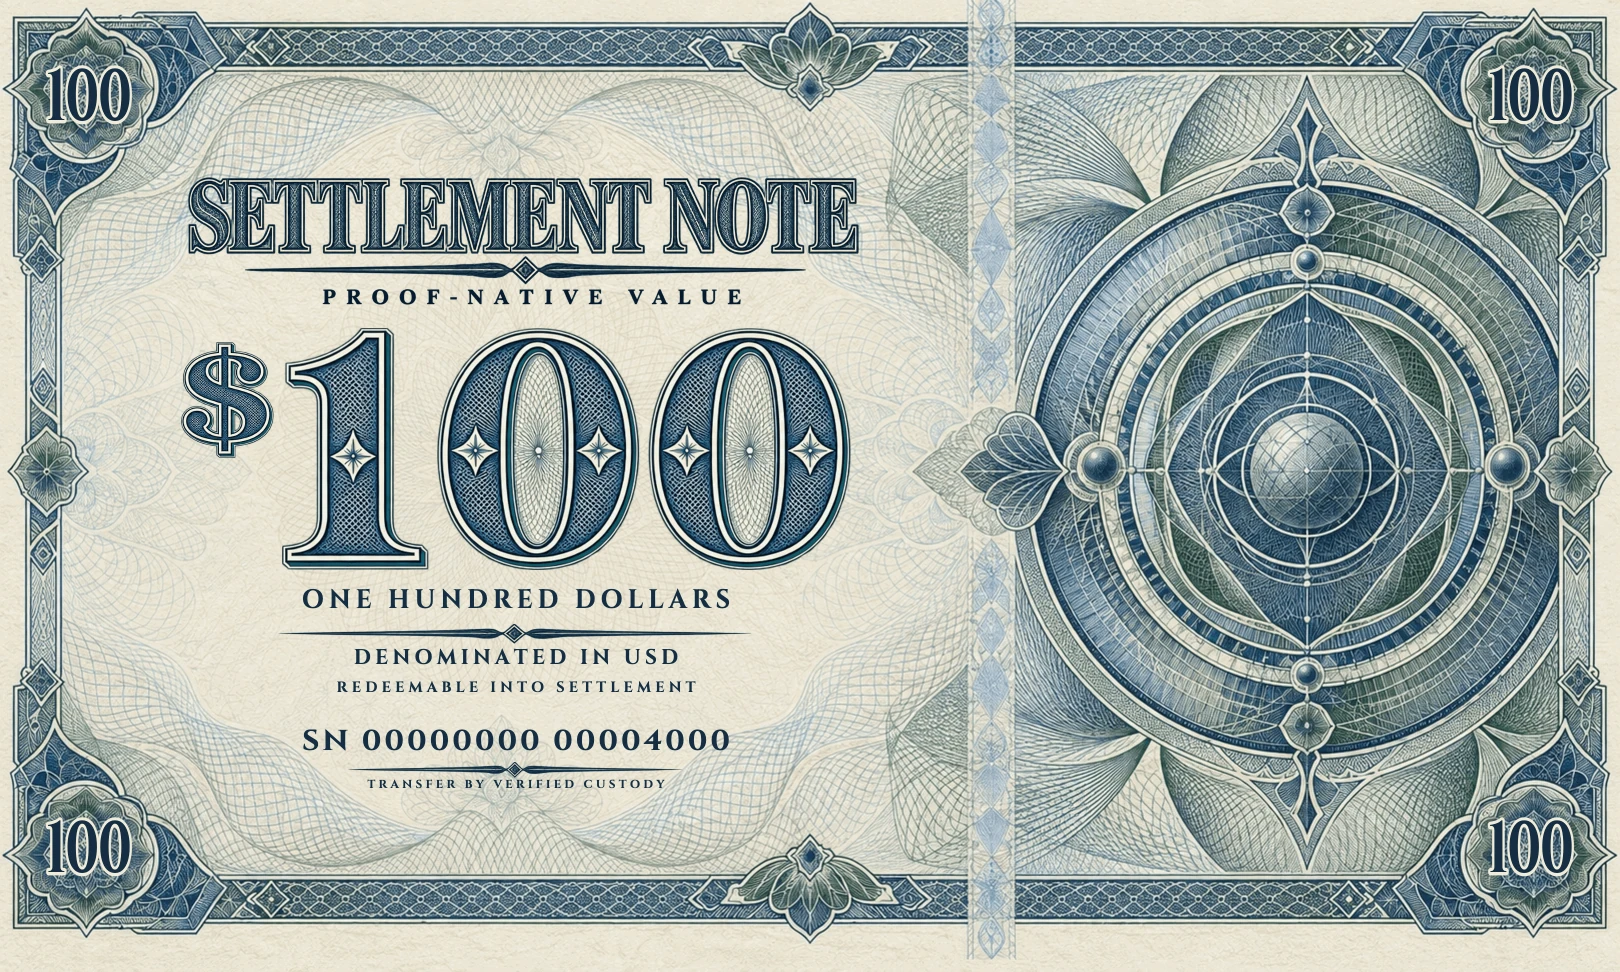
Settlement Note
Proof-native value.Illustrative $100 designs. Unissued specimens, with no spendable value.
Keep it with you.
Save the original note on your device. Its amount and carried history stay with you, even offline.
Give with confidence.
Transfer ownership with a funded Reserve Note. Your recipient can verify the original and see the history that comes with it.
Put it back to work.
Deposit a Reserve Note back into Reserve. Ownership is checked before credit, so the same note cannot be credited twice.
Your proof stays with you
Your Identity Seal and saved originals stay in your hands when a website or service is unavailable. You hold the source, rather than only a link to a page. Offline verification uses the original and the matching verifier on your device; a completed transfer records the change in ownership.
The receiving standard
Receiving institutions must demonstrate that they can verify the value, preserve ownership and history, and maintain continuity. Until assessed, conformance is not demonstrated. A verified failure of continuity requirements is nonconforming for proof continuity within the assessed receiving capability until corrected and reassessed. Payment availability is checked separately.
Leaving proof-native rails
You are moving value outside proof continuity when the destination does not preserve it. Your transfer receipt remains verifiable; the receiving balance may not carry the same proof and history. Before you authorize an available route, its review should show what continuity the destination preserves.
Charts and Kai days
Charts show retained account observations for Total, Reserve and Settlement. Touch or pointer inspection reveals exact amounts and local timestamps. Settlement change compares with the last observed balance before the start of the current Kai day. The v129 day lattice is 17,491,270,421 micro-pulses; an absent opening observation is not treated as a zero balance.
Payment requests
A QR code, shared link or programmed NFC tag opens a payment request inside the bank. It does not send money automatically. The sender reviews the recipient, amount and available value route before any supported execution.